
Checklist
Documents you need for a mortgage application
The CFPB’s list: pay stubs for the last 30 days, W-2s for the last 2 years, signed federal tax returns for the last 2 years, proof of any other income, your 2 most recent bank statements, proof of where the down payment comes from (with a signed letter for any gift), a photo ID, your Social Security number and name change papers if your name changed recently. Self-employed borrowers, VA borrowers and anyone counting child support or alimony need more. Every lender adds its own requests, so ask each one for its list.

This is general information, not financial or legal advice. Each lender and loan program sets its own requirements and they change. Ask your lender for its written list.
Start this list before you shop for a loan. The CFPB suggests gathering everything early, because even a lender that doesn’t need a paper now may ask for it later in underwriting.
Identity
- Photo ID: usually a driver’s license or a non-driver ID, for every borrower.
- Social Security number: for each borrower, for the credit check.
- Name change papers: a marriage certificate, divorce decree or court order, if your name changed recently.
- Residency papers: if you aren’t a US citizen, ask the lender which immigration documents they need.
Income
- Pay stubs: covering the last 30 days, the most recent ones.
- W-2 forms: for the last 2 years, from every employer.
- Federal tax returns: signed, for the last 2 years, with all schedules.
- Other income: award letters for Social Security, pension or disability income, and leases for rental income. The lender needs proof that this income can reasonably be expected to continue.
- Child support or alimony: the court order that sets the amount, and proof that the payments arrive. The CFPB warns that irregular payments, or payments that end within 3 years, may not count.
- Self-employed or seasonal income: more documentation, and it varies by lender. Lenders often ask for business tax returns and a year-to-date profit and loss statement.
- A new job: a signed offer letter, if you’re changing employers before closing.
Down payment and savings
- Bank statements: the 2 most recent, every page, even pages marked “intentionally left blank”.
- Investment and retirement statements: showing at least 2 months of ownership, if that money goes toward the down payment.
- Gift letter: a signed statement from the giver that the money is a gift, plus proof of the transfer.
- Large deposit explanations: a short letter and the paper trail for any deposit that isn’t your pay.
- Earnest money: the receipt or canceled check, once you’ve made an offer.
Debts and credit
- Statements for current debts: car loans, student loans and credit cards, so the lender can match them to your credit report.
- Letters of explanation: short, signed and dated, for late payments or credit inquiries the lender asks about.
- Court papers: for a bankruptcy, a judgment or a divorce that the lender asks about.
Special cases
- VA loans: a Certificate of Eligibility from the VA, which servicemembers, veterans and some surviving spouses need to qualify.
- Homebuyer education: the certificate from a housing counseling or homebuyer course, if you took one.
- Refinancing: your current mortgage statement and homeowners insurance details.
After you apply
Underwriting brings a second round of requests. The CFPB’s advice:
- Answer quickly, and check email, voicemail and mail often.
- Send copies and keep the originals.
- Include every page, and print the web address on statements you download.
- Get exact instructions for how to send, and confirm the right person received it.
Fresh statements and pay stubs replace old ones as the weeks pass, so keep the set current until closing. Then the house-buying papers take over: see the documents to buy a house.
Mistakes that get files sent back
- Missing pages, especially the blank last page of a bank statement.
- Unsigned tax returns, or returns without their schedules.
- Unexplained transfers between accounts.
- Photos taken at an angle, with the edges or the dates cut off.
- New debt during underwriting. A car loan or a new card can change what you qualify for.
Scan and send them safely
- Scan each paper as one PDF with every page in order. Several pages into one PDF shows how.
- Name files the way lenders file them: “2025 W-2 Acme.pdf”, “Checking Sept-Oct.pdf”.
- Upload through the lender’s secure portal. The CFPB says email is never a secure way to send financial information.
- If a portal limits file size, make the PDF smaller instead of splitting statements.
- Never follow wiring instructions that arrive by email. Call your closing agent at a number you already know.
How long to keep these papers after closing covers the next step.
Where Scanner One helps, and where it doesn’t
Notes and the Files app can scan a few pages into one document, and if your lender has a portal that takes photos, that may be all you need.
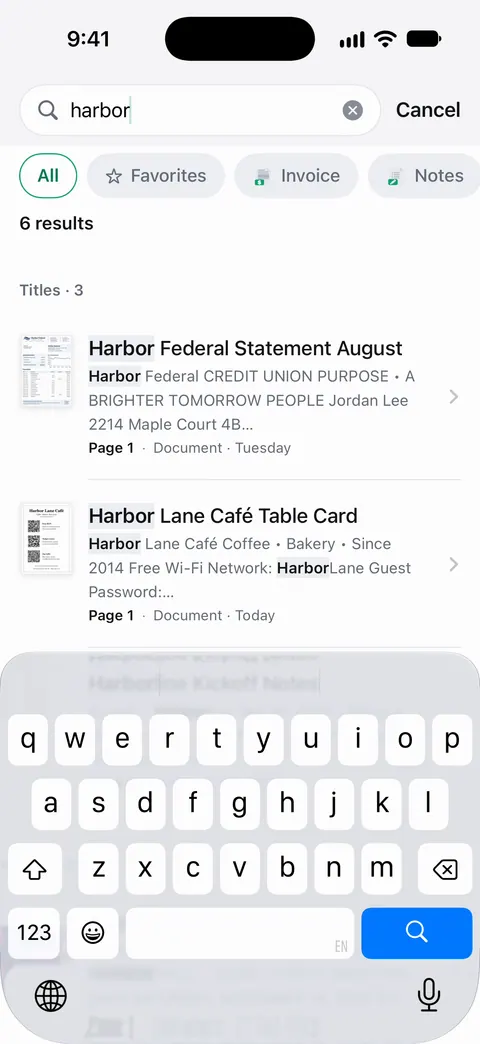
Scanner One is built for a pile like this one. Point your camera at any piece of paper. Scanner One finds the edges, straightens the page, cleans it up and saves a real PDF. A scan can have many pages, and you can reorder them. Scanner One makes searchable PDFs. Search looks inside the text of every document and shows the matching line and page. When the underwriter asks for “the October statement” again, you can find it by a word on the page.
The PDF tools merge, split, compress, password-protect, add page numbers and watermarks, and extract text. Free accounts can run them 3 a week. On a free account, pages you share, print or export carry a small “Scanned with Scanner One” label at the bottom right. Pro removes it. Documents stay on your iPhone unless you share them or turn on iCloud Sync.
Packs: say what you’re applying for, like a visa, a lease or your taxes, and see which papers you have and what’s missing.
Scanner One doesn’t talk to your lender’s portal, check your file against a lender’s rules, or tell you what you qualify for.
Questions and answers
How many months of bank statements do mortgage lenders want?
The CFPB’s list says your 2 most recent statements, every page, including pages marked blank. For retirement or investment money used toward the down payment, it asks for statements showing at least 2 months of ownership. Your lender may ask for more.
What is a gift letter?
A signed statement from the person giving you money for the down payment, saying it is a gift and not a loan. Some loan types don’t allow gift funds, so ask your loan officer early.
Why does the lender ask about a deposit in my bank statement?
Lenders must verify where your down payment comes from, so they ask you to document large deposits that aren’t your pay. A transfer between your own accounts is common: send the statement from the other account that shows the money leaving it.
Do I need tax returns if I have W-2s?
Usually yes. The CFPB’s list includes both W-2s and signed federal tax returns for the last 2 years. If you are self-employed, expect to send more, such as business returns.
Sources
What this page says about Scanner One was checked against the app on .
- CFPB, Create a loan application packet — the core list of documents; last modified 2024-12-12
- CFPB, Gather and update your paperwork — VA certificate, child support and alimony, self-employed income; last modified 2024-12-12
- CFPB, Submit documents and answer requests from the lender — large deposits, gift funds, sending copies and every page; last modified 2024-12-12
- CFPB, Mortgage closing scams: how to protect yourself and your closing funds — never follow wiring instructions in an email, email is not secure for financial information; archived post, last modified 2026-06-25
- Apple Support, Scan documents on your iPhone or iPad (108963) — scanning several pages in Notes and Files; published 2026-02-13
- Scanner One on the App Store — the app’s own listing
Get Scanner One
Scanner One is free, with generous limits: scanning, clean PDFs and text search never stop.

Scanner OneScan, sign and ask anything
Scanner One is free, with generous limits: scanning, clean PDFs and text search never stop.